2%
General inflation
How fast everyday prices rise each year in the plan — the central bank’s published target.
FIRE Planner · FIRE calculator for Thailand
Nivritee’s FIRE Planner projects when your household could stop working, in baht, with Thai inflation, a medical cost rate of its own and your Social Security Fund, Provident Fund and RMF balances pre-filled as rows. It is free: eight answers after sign-up, about two minutes.
Your Location
| Country | Currency | Inflation | Medical |
|---|---|---|---|
| Thailand | THB | 2.0% | 10.8% |
| India | INR | 4.0% | 12.9% |
| United Kingdom | GBP | 2.0% | 10.0% |
| Singapore | SGD | 2.0% | 16.9% |
Fourteen countries. Every rate shown, every rate yours to change.
FIRE Planner · your FI number in THB
Your FI number is a year of the life you plan after you stop working, divided by the 3.5% withdrawal rate the planner uses for Thailand, with tax on withdrawals allowed for, your goals added and income that keeps paying netted off. It is projected in THB (฿), with a Financial Freedom Index out of 100 beside it.
Thailand publishes household income rather than household wealth, so your peer percentile compares your household’s income with the NSO Household Socio-Economic Survey, aged forward from its survey year.
How the FIRE Planner works →Financial freedom index
An illustrative household. Your own score is computed from your plan and stored, not estimated.
Thailand · the rates your plan starts from
A plan for Thailand starts from these, in THB. Each one is shown on your plan and yours to change, and changing one changes nobody else’s.
2%
How fast everyday prices rise each year in the plan — the central bank’s published target.
1.31%
School and university fees, which rise faster than everyday prices.
10.8%
Healthcare costs, which rise faster than everyday prices in almost every market.
6.2%
An assumption, not a forecast — shown so you can change it.
3.71%
Lower, because money being drawn on is usually held more cautiously.
3.5%
What your FI number assumes you draw from your savings in a year.
Portfolio Tracker · Thailand schemes in one plan
Each is a row in your plan, under its own name, beside your stocks, funds and deposits in any other country — all converted into one currency in the Portfolio Tracker.
How the Portfolio Tracker works →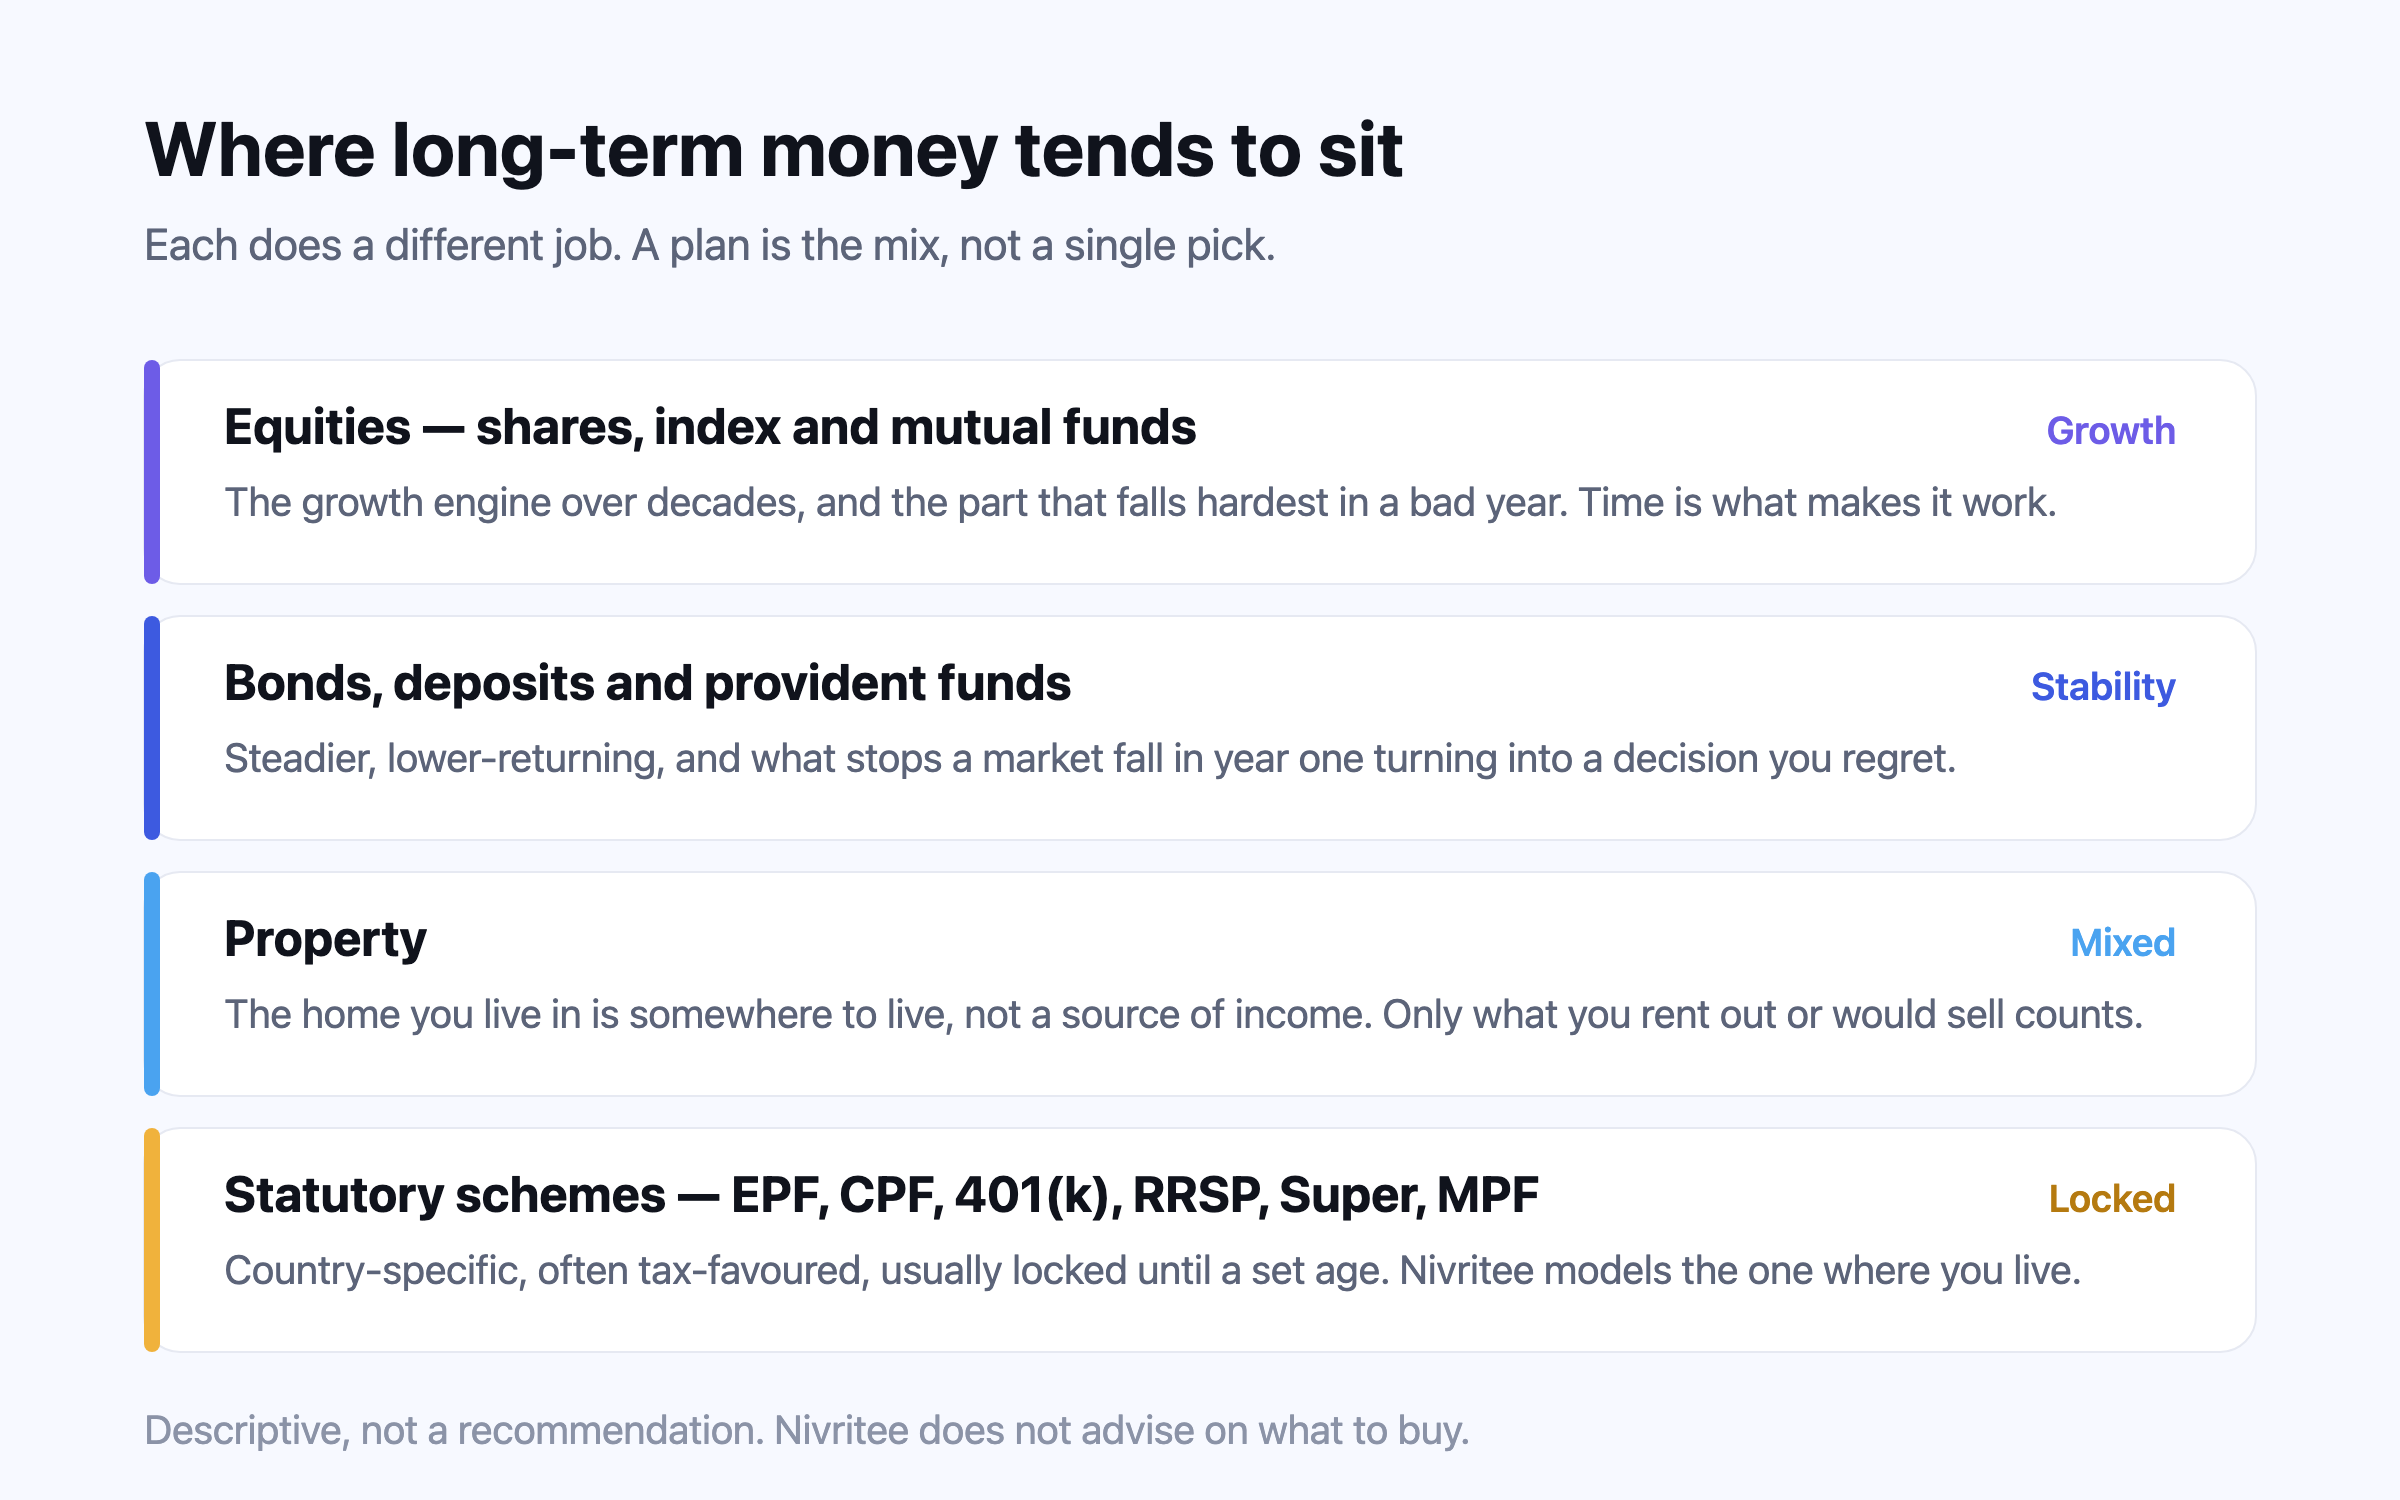
Thailand · when the money can be reached
The ages that decide how a FIRE plan bridges the years after the salary stops.
RMF gains are free of income tax once you are at least 55 and have bought units in at least five consecutive years.
The Long-Term Resident visa has a Wealthy Pensioner category for people aged 50 and over with a qualifying passive income; a salary does not count towards it.
FIRE Planner · Thailand
Thai savings for later sit in several places — the Social Security Fund, an employer’s Provident Fund, RMF and Thai ESG units — and each opens on its own terms. Provident Fund contributions are deductible up to 15% of wages, within a 500,000-baht cap. Nivritee pre-fills each as its own row and shows the years before they open.
Nivritee grows medical costs at their own rate rather than general inflation; insurers in WTW’s survey project a 10.8% medical cost trend for Thailand in 2026.
Prices are grown at 2%, the middle of the Bank of Thailand’s 1–3% medium-term inflation target. Like every rate in the plan, you can change it.
Settling in Thailand with money abroad? Foreign income a Thai tax resident earns from 2024 onward is taxable when it is brought into Thailand, even in a later year. Nivritee holds savings in other currencies in one baht plan.
Thailand publishes household income rather than wealth, so your peer percentile compares your household’s income with Thai households in the National Statistical Office’s Household Socio-Economic Survey, and the card says so.
Why Nivritee for Thailand
Your Thailand plan reads the same figures as the other five pillars — what you hold, earn, spend and owe, in whichever countries they are in.
Portfolio Tracker
Stocks, funds and deposits from every country you invest in, valued daily in one home currency, with your real return (XIRR).
Portfolio Tracker →Money Manager
What you earn, spend and owe, benchmarked against your country, your city and each kind of inflation.
Money Manager →Family Finance
Plan as a couple with your own logins, choose what each of you sees, and give your CA or lawyer read-only access.
Family Finance →Niv
Analyses your portfolio, spending, buckets and plan, runs what-ifs on the real projection, and explains. You decide.
Niv →Freedom Ladder
Survival, Sustenance, Sufficiency, Surplus: how much belongs in each bucket, and whether it is in something that bucket can use.
Freedom Ladder →What only Nivritee does
FIRE calculators start from a figure you type. The FIRE Planner starts from everything your household holds, in every country, in one currency — and plans for both of you.
Indian mutual funds, US stocks, a UK fund and a Gulf deposit in one household figure, converted daily into your home currency.
What you hold today feeds the projection of when you could stop. Portfolio trackers do not plan; FIRE calculators do not track.
Two people, one plan, each choosing what the other sees — and your CA or lawyer sees exactly what you share, read-only.
Fourteen markets’ inflation, schemes and household surveys, so your spending and your percentile are measured where you live.
Ask Niv a what-if and she runs it on your own projection and reports both figures — she never guesses at arithmetic.
No fee, no commissions, no products. Nobody at Nivritee can open your plan.
FIRE calculator Thailand · questions
The common rule of thumb is 25 times a year’s spending: a 4% first-year withdrawal, raised with inflation, lasted at least 30 years through US market history in William Bengen’s 1994 study. Nivritee’s FI number for Thailand uses a more cautious 3.5% withdrawal rate — about 29 times a year’s need — allows for tax on withdrawals, adds your goals and nets off income that keeps paying.
RMF gains are exempt once you are at least 55 and have bought units in at least five consecutive years. Nivritee holds your RMF as its own row, so the years before 55 are visible in the ledger.
The Board of Investment’s Long-Term Resident visa has a Wealthy Pensioner category for people aged 50 and over with a qualifying passive income. Foreign income a Thai tax resident earns from 2024 onward is taxable when it is brought in. Nivritee projects in baht with savings held in any currency.
Yes. Nivritee’s FIRE Planner is free, with no paid tier. Once you have an account it asks eight questions — about two minutes — and projects your plan year by year in baht with Thai inflation and your Social Security Fund, Provident Fund and RMF. You get your FI number, a 0–100 Financial Freedom Index, eight stress tests and how your household income compares with Thai households.
About two minutes to a first answer from eight figures, then add your holdings, your partner and the detail at your own pace. Free, no bank login, and nobody at Nivritee can open your plan.
Start free