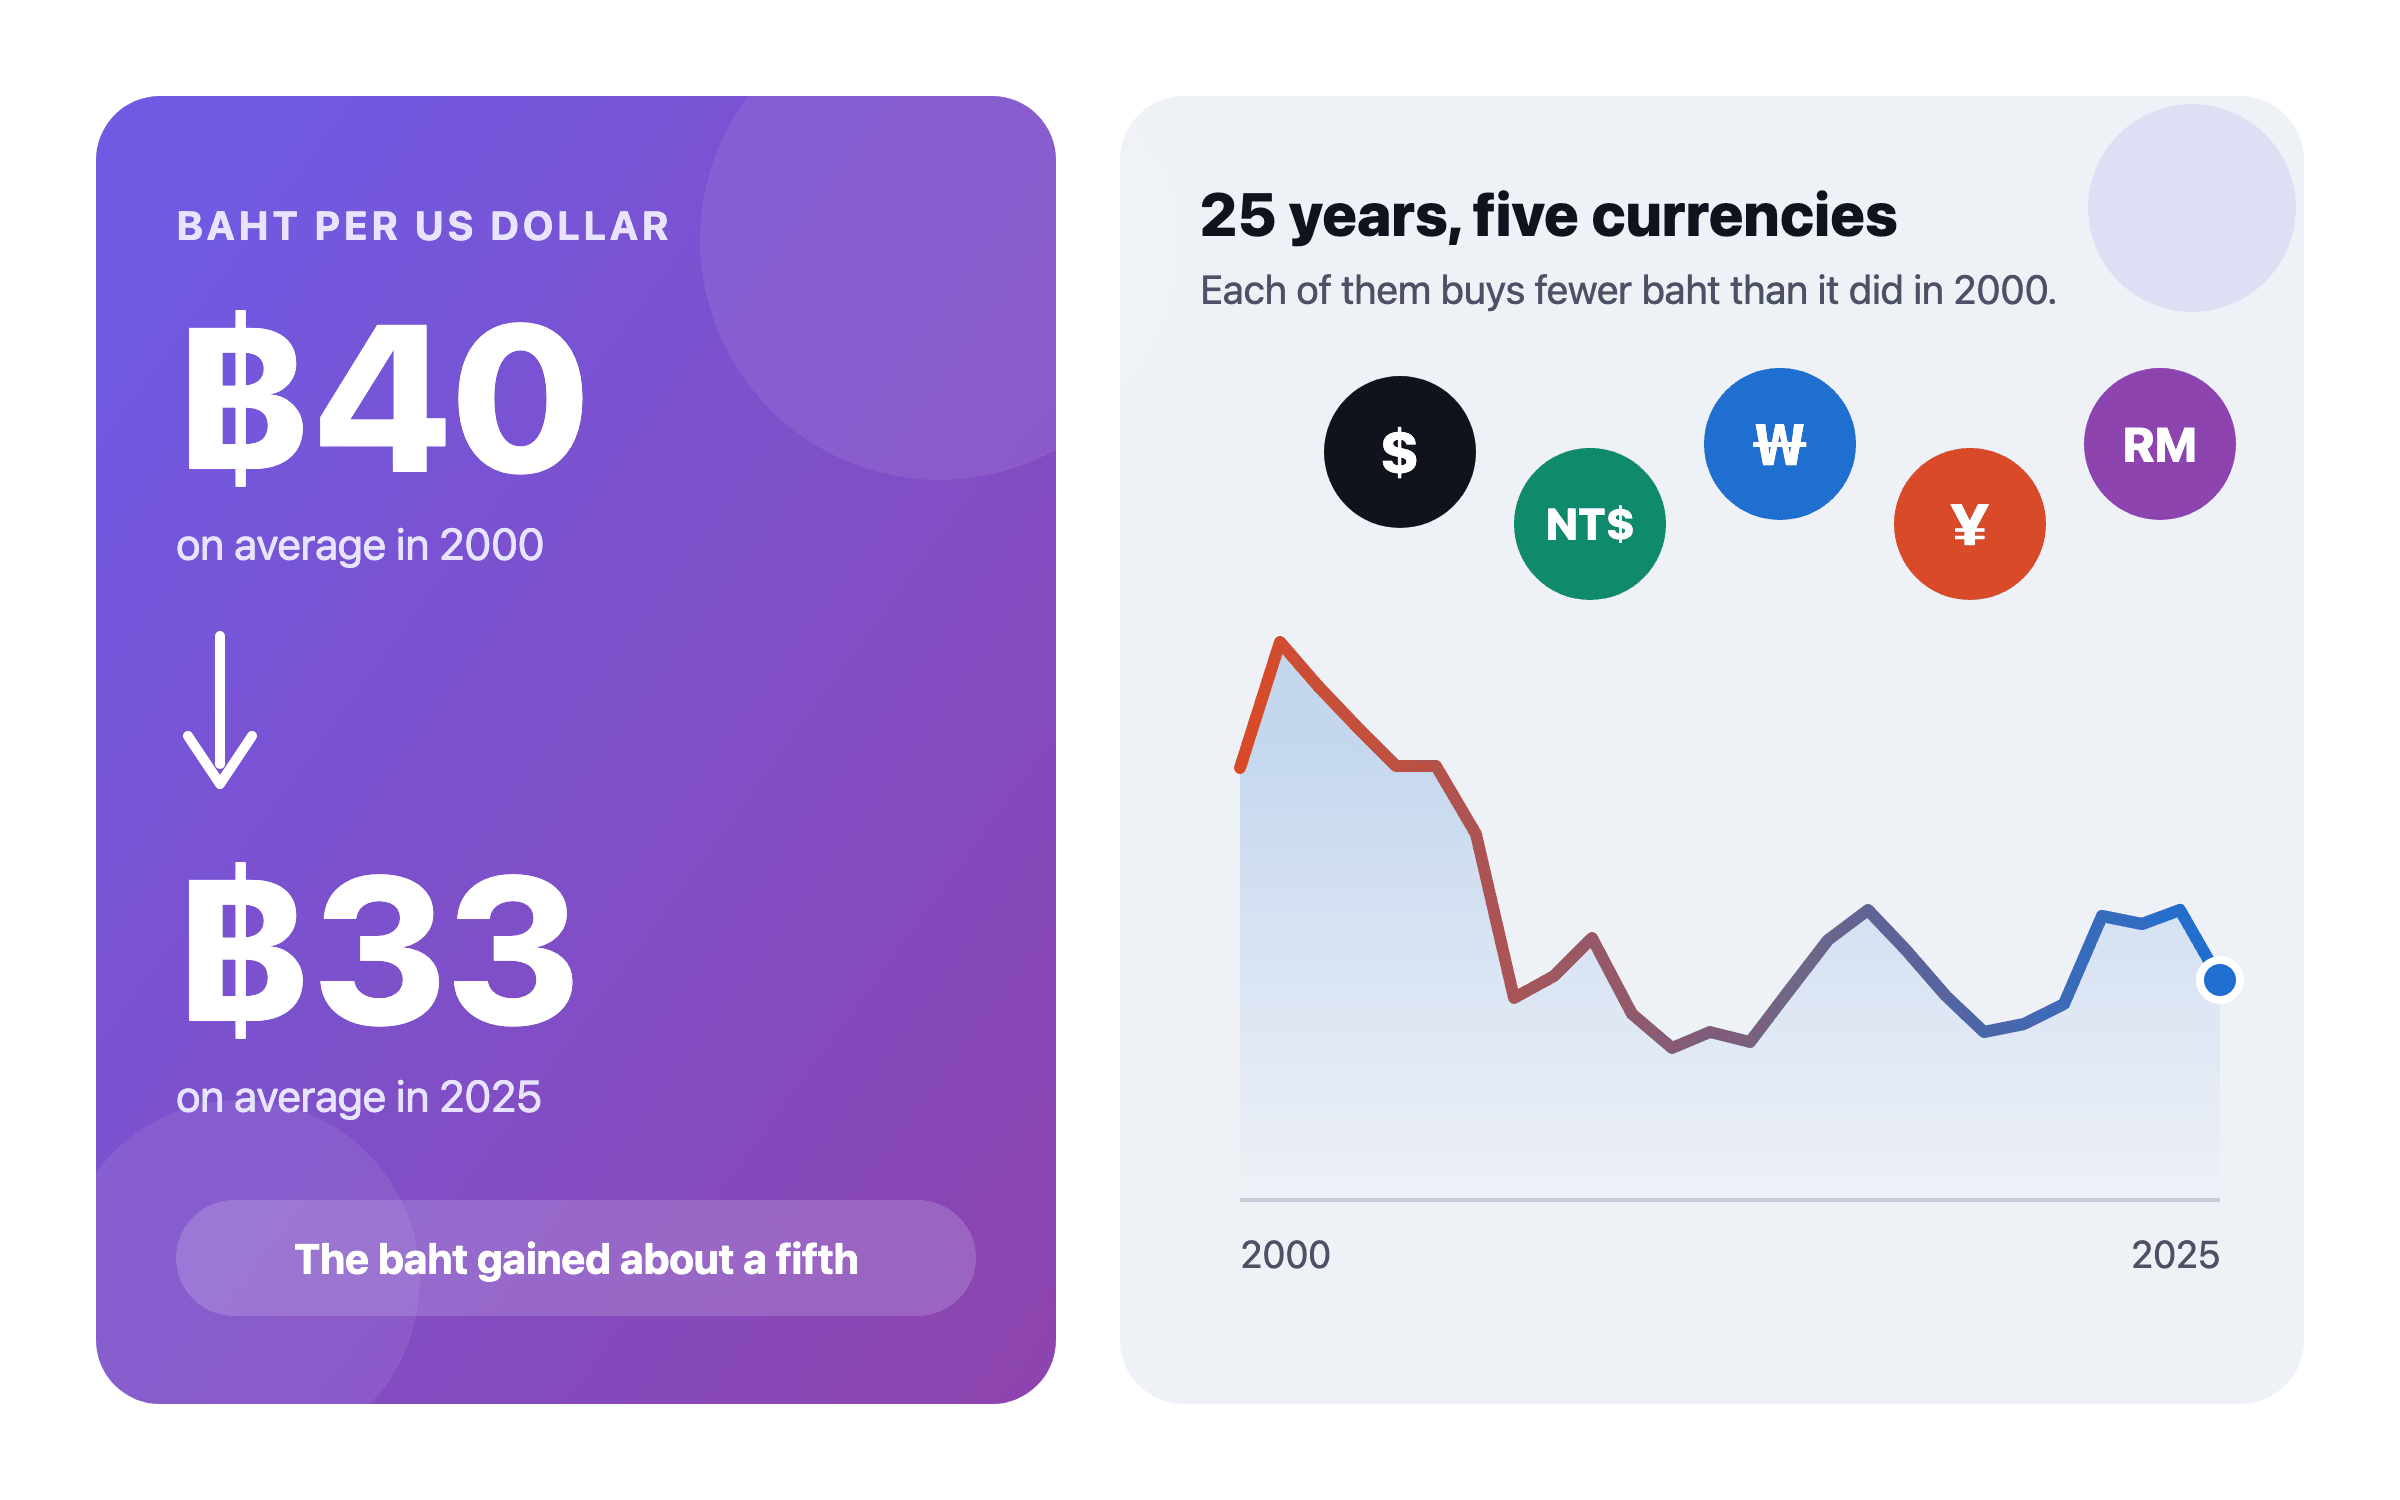
Since 2000 the baht has gained against the dollar, the yen, the won, the ringgit and the Taiwan dollar, so money earned abroad buys fewer baht than it did.
A dollar bought ฿40.21 on average in 2000 and ฿32.86 in 2025, and 100 yen fell from ฿37.30 to ฿21.97. Lower inflation in Thailand than in the US explains the direction. For a Thai earning abroad and spending in baht later, the lesson is to judge savings in baht, the currency they will finally be spent in.
Nivritee Research · 29 October 2026 · 6 min read
In 2000 a US dollar bought ฿40.21 on average. In 2025 it bought ฿32.861. In 2026 to 23 October the average was ฿32.58, and on 23 October a dollar bought ฿33.762. Over the 25 years to 2025 the baht price of a dollar fell by 18%, or 0.80% a year on average; put the other way, the baht gained about 22% against the dollar1. That is the opposite of what many families expect of an Asian currency, and it matters most to the people who earn abroad and plan to spend in Thailand later. This report sets out the baht against six currencies Thais abroad earn in, explains why it rose, and works through what that did to savings held on each side.
First, 1997
Any history of the baht starts with the crisis. Thailand has run a managed float since 2 July 1997, the Bank of Thailand says, intervening when the baht moves too sharply but without targeting a rate or pegging it to another currency3. The change was abrupt. In the Federal Reserve’s daily series a dollar bought ฿24.52 on 1 July 1997 and ฿30.18 on 2 July, and on 12 January 1998 it bought ฿56.102. Measured by yearly averages, a dollar cost ฿25.36 in 1996, ฿31.07 in 1997 and ฿41.26 in 1998, 63% more than two years earlier1.
Baht needed to buy one US dollar, yearly averages, 1995 to 2025.
A rising line is a weaker baht. The jump of 1997 and 1998 has not been repeated; since 2007 a dollar has cost between about 30 and 35 baht on a yearly average. 1The figures in this chart
Baht per US dollar
1995
฿24.92
1996
฿25.36
1997
฿31.07
1998
฿41.26
1999
฿37.89
2000
฿40.21
2001
฿44.53
2002
฿43.02
2003
฿41.56
2004
฿40.27
2005
฿40.25
2006
฿37.88
2007
฿32.20
2008
฿32.96
2009
฿34.31
2010
฿31.70
2011
฿30.46
2012
฿31.05
2013
฿30.70
2014
฿32.46
2015
฿34.24
2016
฿35.26
2017
฿33.91
2018
฿32.30
2019
฿31.04
2020
฿31.31
2021
฿32.01
2022
฿35.05
2023
฿34.78
2024
฿35.28
2025
฿32.86
Most of what followed was a slow recovery. The yearly average peaked at ฿44.53 in 2001, was back to ฿40.25 in 2005 and fell to ฿32.20 in 20071. Since then a dollar has never averaged more than ฿35.28 in a year, which it reached in 20241. For the rest of this report the starting point is 2000, so that the crisis itself does not decide the result.
Twenty-five years in six currencies
Thai workers go where the jobs are. In the Department of Employment’s ranking reported by Thai PBS in October 2023, Taiwan was the largest destination for Thai workers, followed by Israel, South Korea, Japan and Malaysia4. The table and charts below use the currencies of those places that the Federal Reserve publishes, plus the US dollar and the Singapore dollar. The Israeli shekel is not in the Federal Reserve’s series, so it is left out rather than taken from a different source on a different basis.
Annual averages of daily rates. The dollar column is the Federal Reserve’s baht-dollar series; the others divide it by the Federal Reserve’s series for each currency against the dollar. 2026 is the average of the published days to 23 October. 1,2,5,6,7,8,9
Year
Baht per US dollar
per Taiwan dollar
per 1,000 Korean won
per 100 Japanese yen
per Malaysian ringgit
per Singapore dollar
2000
40.21
1.29
35.56
37.30
10.58
23.31
2005
40.25
1.25
39.32
36.56
10.63
24.19
2010
31.70
1.01
27.43
36.11
9.85
23.26
2015
34.24
1.08
30.28
28.29
8.77
24.91
2020
31.31
1.06
26.52
29.32
7.45
22.69
2025
32.86
1.05
23.12
21.97
7.68
25.15
2026 (January to 23 October)
32.58
1.03
22.45
20.56
8.11
25.48
Baht needed to buy each currency, as an index with 2000 = 100, yearly averages, 2000 to 2025.
Taiwan dollar
US dollar
Malaysian ringgit
Korean won
Japanese yen
A line below 100 means that currency buys fewer baht than it did in 2000. All five ended below it. The ringgit line matches the dollar line until 2004 because the ringgit stood at exactly 3.80 to the dollar in every year from 2000 to 2004. 1,5,6,7,8The figures in this chart
Taiwan dollar
US dollar
Malaysian ringgit
Korean won
Japanese yen
2000
100.0
100.0
100.0
100.0
100.0
2001
102.4
110.7
110.7
96.9
98.2
2002
96.8
107.0
107.0
96.8
92.1
2003
93.9
103.3
103.3
98.0
96.1
2004
93.8
100.2
100.2
98.9
99.8
2005
97.4
100.1
100.5
110.6
98.0
2006
90.6
94.2
97.6
111.6
87.3
2007
76.2
80.1
88.6
97.5
73.3
2008
81.3
82.0
93.6
84.4
85.5
2009
80.8
85.3
92.0
75.7
98.2
2010
78.2
78.8
93.1
77.1
96.8
2011
80.6
75.8
94.2
77.4
102.5
2012
81.7
77.2
95.1
77.6
104.3
2013
80.4
76.3
92.1
78.9
84.3
2014
83.3
80.7
93.8
86.8
82.3
2015
83.9
85.2
82.9
85.2
75.8
2016
85.1
87.7
80.6
85.5
87.0
2017
86.7
84.3
74.6
84.5
81.1
2018
83.4
80.3
75.7
82.6
78.5
2019
78.1
77.2
70.8
74.9
76.3
2020
82.6
77.9
70.4
74.6
78.6
2021
89.1
79.6
73.0
78.6
78.1
2022
91.4
87.2
75.3
76.3
71.5
2023
86.8
86.5
72.1
74.9
66.4
2024
85.4
87.8
72.9
72.8
62.5
2025
82.0
81.7
72.5
65.0
58.9
The yen fell furthest. A hundred yen bought ฿37.30 on average in 2000 and ฿21.97 in 2025, 41% less; a thousand won fell from ฿35.56 to ฿23.12, 35% less7,6. The ringgit lost 27% and the Taiwan dollar 18%, about as much as the US dollar8,5. The Singapore dollar is the exception in the table: it rose from ฿23.31 to ฿25.15, because it strengthened against the US dollar by more than the baht did9.
The average yearly change, and why the average misleads
Measured from the 2000 average to the 2025 average, the baht price of a yen fell by 2.09% a year, of a won by 1.71%, of a ringgit by 1.28%, of a US dollar by 0.80% and of a Taiwan dollar by 0.79%, while the baht price of a Singapore dollar rose by 0.30% a year1,7,6,8,5,9.
How fast the baht price of each currency changed, on average, from 2000 to 2025.
Compound yearly rate of change between the 2000 and 2025 annual averages. A longer bar below zero means that currency lost value against the baht faster. 1,7,6,8,5,9The figures in this chart
Average yearly change in baht per unit, % (negative: the baht rose)
Japanese yen
−2.09%
Korean won
−1.71%
Malaysian ringgit
−1.28%
US dollar
−0.80%
Taiwan dollar
−0.79%
Singapore dollar
0.30%
A fall of 0.80% a year in the baht price of a dollar never happened in any particular year. Between the 2000 and 2005 averages it rose by 0.02% a year, then from 2005 to 2010 it fell by 4.66% a year, the fastest stretch of the period, and from 2010 to 2015 it rose again by 1.55% a year1. Within years the swings were larger still. On 19 April 2013 a dollar bought ฿28.60, the strongest the baht has been in the daily series since the float; by 27 December 2013 it bought ฿32.852. On 14 October 2022 it bought ฿38.28, and on 23 February 2026 ฿30.962.
How fast the baht price of a dollar changed in each five-year period.
Compound yearly rate between annual averages. Two of the five stretches went against the long-run direction, which is why a plan should allow for both rather than assume a steady drift. 1The figures in this chart
Average yearly change in baht per dollar, % (negative: the baht rose)
2000 to 2005
0.02%
2005 to 2010
−4.66%
2010 to 2015
1.55%
2015 to 2020
−1.78%
2020 to 2025
0.97%
Why the baht rose: the inflation gap
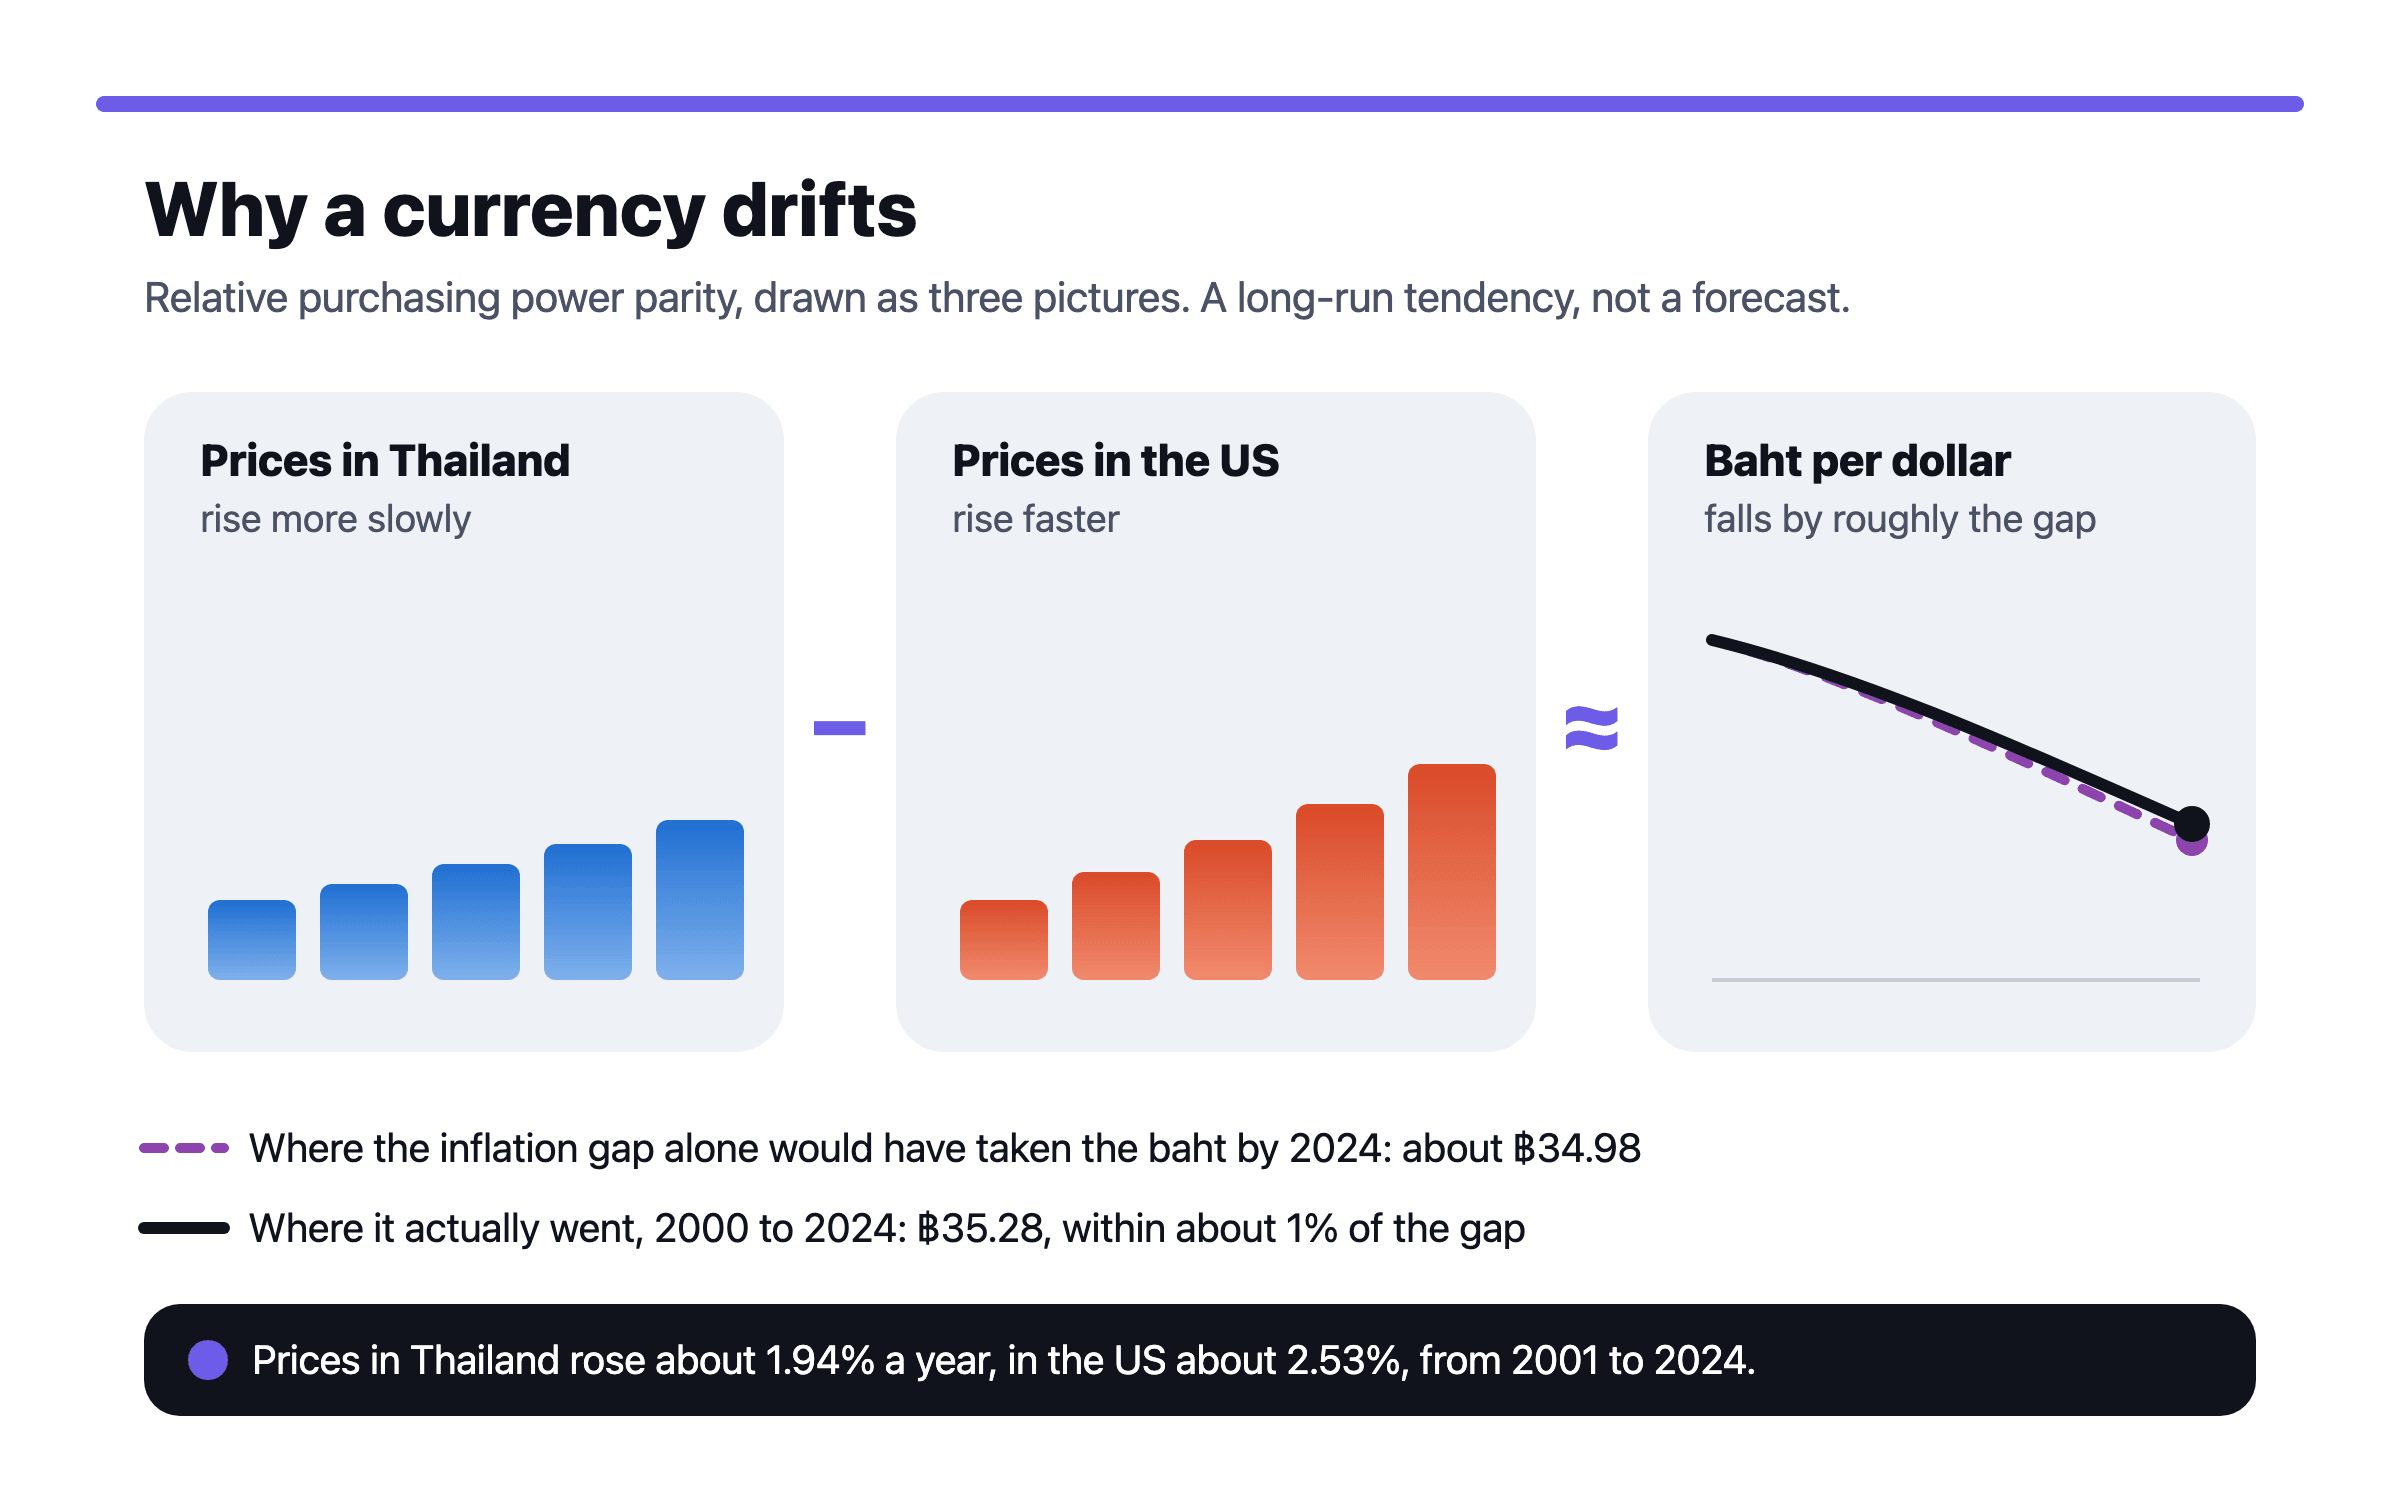
The usual explanation is relative purchasing power parity: over long periods, a currency tends to move against another by roughly the gap between their inflation rates, because otherwise goods in one would keep getting cheaper than in the other. From 2001 to 2024 consumer prices in Thailand rose by 1.94% a year on average, and in the US by 2.53%, so Thailand’s price level multiplied by 1.58 while America’s multiplied by 1.8210,11. Prices rose more slowly in Thailand, so the baht had room to rise.
Average yearly fall in the baht price of a dollar, 2000 to 2024
If the exchange rate had tracked that gap exactly, a dollar would have cost about ฿34.98 in 2024. It cost ฿35.28 instead1,10,11. Over these 24 years the baht came within about 1% of where the inflation gap alone would have taken it, which is unusually close: the rupee, by contrast, fell by much less than India’s inflation gap implied, as our rupee report shows. Parity is a long-run tendency, not a law; the years above show how far a rate can wander from it in the meantime.
Relative purchasing power parity: when one country’s prices rise more slowly than another’s, its currency tends to strengthen by roughly the difference. It is a long-run tendency, not a forecast for any one year.
Parity says nothing about the level, only the direction. The World Bank’s purchasing power parity for household consumption in Thailand was ฿10.61 per international dollar in 2025, against a market rate of ฿32.8612,1. Put simply, converted at the market rate, what Thai households buy cost about 32% of what the same basket cost in the US. And the inflation gap itself is not fixed. The Bank of Thailand’s target for headline inflation is a range of 1% to 3% over the medium term13, and Thai consumer prices fell by 0.13% in 2025, below that range10.
What it did to savings kept abroad
Take two illustrative cousins working in Japan in 2000. Each sets aside ¥1,000,000, worth ฿372,990 at that year’s average rates1,7. One keeps it in yen; the other sends it home and keeps baht. To isolate the currency, assume neither earns any interest. By 2025 the yen were worth ฿219,711, while the baht cousin still had ฿372,9901,7. A third, working in the US, who kept $10,000 from 2000 saw it go from ฿402,098 to ฿328,619 over the same years1.
Now ask what each could buy at home. Thai consumer prices rose 1.58 times from 2000 to 2025, so a basket that cost ฿372,990 in 2000 cost about ฿590,200 in 202510. The cousin who kept yen could buy 37% of that basket, the cousin who kept baht 63%. The dollar saver’s money bought 52% of the basket the same dollars bought in 20001,7,10.
Judge savings in the currency you will spend
The question is never whether the baht is strong or weak. It is which currency your later life will be paid in. A household that will settle in Thailand carries baht costs; yen, won or dollar savings are a bet on the baht weakening, and over these 25 years that bet mostly lost. A household that will stay in Taipei, Seoul or Osaka carries costs in that currency, and baht savings are the bet. Our article on home bias and currency risk works through how to hold both without losing the match.
Measure the corpus in baht if you will spend in baht. A balance that grew in yen or won can still have shrunk in baht: 100 yen bought 41% fewer baht in 2025 than in 20007.
Do not plan on a steady drift either way. In the five-year stretches above, the baht price of a dollar changed by anything from a fall of 4.66% a year to a rise of 1.55% a year1. A plan that only works if the baht keeps rising, or keeps falling, is a currency bet.
Keep near-term money in the currency it will be spent in. Money for a house in Thailand in two years has no time to recover from a bad exchange-rate year.
Remember the cost of crossing. Every conversion costs something, and small, frequent transfers cost more; see what sending money home costs.
Reading the baht from here
Nobody can tell you where the baht will be next year, and the history above is a record, not a forecast. In 2026 alone a dollar has bought anything from ฿30.96 to ฿33.83 on a single day2. What the record does support is a habit: plan in the currency you will spend, assume costs rise with that country’s inflation, and treat any gain from a currency move as a bonus rather than a foundation. If a weaker dollar is part of your story, our report on the weaker dollar and global families covers 2025 in more detail.
Questions people ask
How much has the baht changed against the dollar since 2000?
From ฿40.21 per dollar on average in 2000 to ฿32.86 in 2025: the baht price of a dollar fell by 18%, or 0.80% a year, so the baht gained about 22%1. In 2026 to 23 October the average was ฿32.582.
What happened to the baht in 1997?
Thailand moved to a managed float on 2 July 19973. In the Federal Reserve’s daily series a dollar bought ฿24.52 on 1 July 1997 and ฿56.10 on 12 January 1998; the yearly average went from ฿25.36 in 1996 to ฿41.26 in 19982,1.
Why has the baht risen against the dollar?
Mainly because prices in Thailand have risen more slowly than in the US: 1.94% a year against 2.53% from 2001 to 202410,11. Over long periods currencies tend to move by roughly their inflation gap, and over these years the baht ended within about 1% of where that gap alone would have taken it.
How much has the yen fallen against the baht?
A hundred yen bought ฿37.30 on average in 2000 and ฿21.97 in 2025, 41% less, a fall of 2.09% a year1,7. In 2026 to 23 October the average was ฿20.562,14.
Should a Thai working abroad keep savings in baht or in the local currency?
It depends on where the money will be spent, not on a view about the baht. Savings that match the currency of your future costs remove one risk; anything else is a currency bet, and over five-year stretches the baht price of a dollar has changed by anything from a 4.66% yearly fall to a 1.55% yearly rise1.
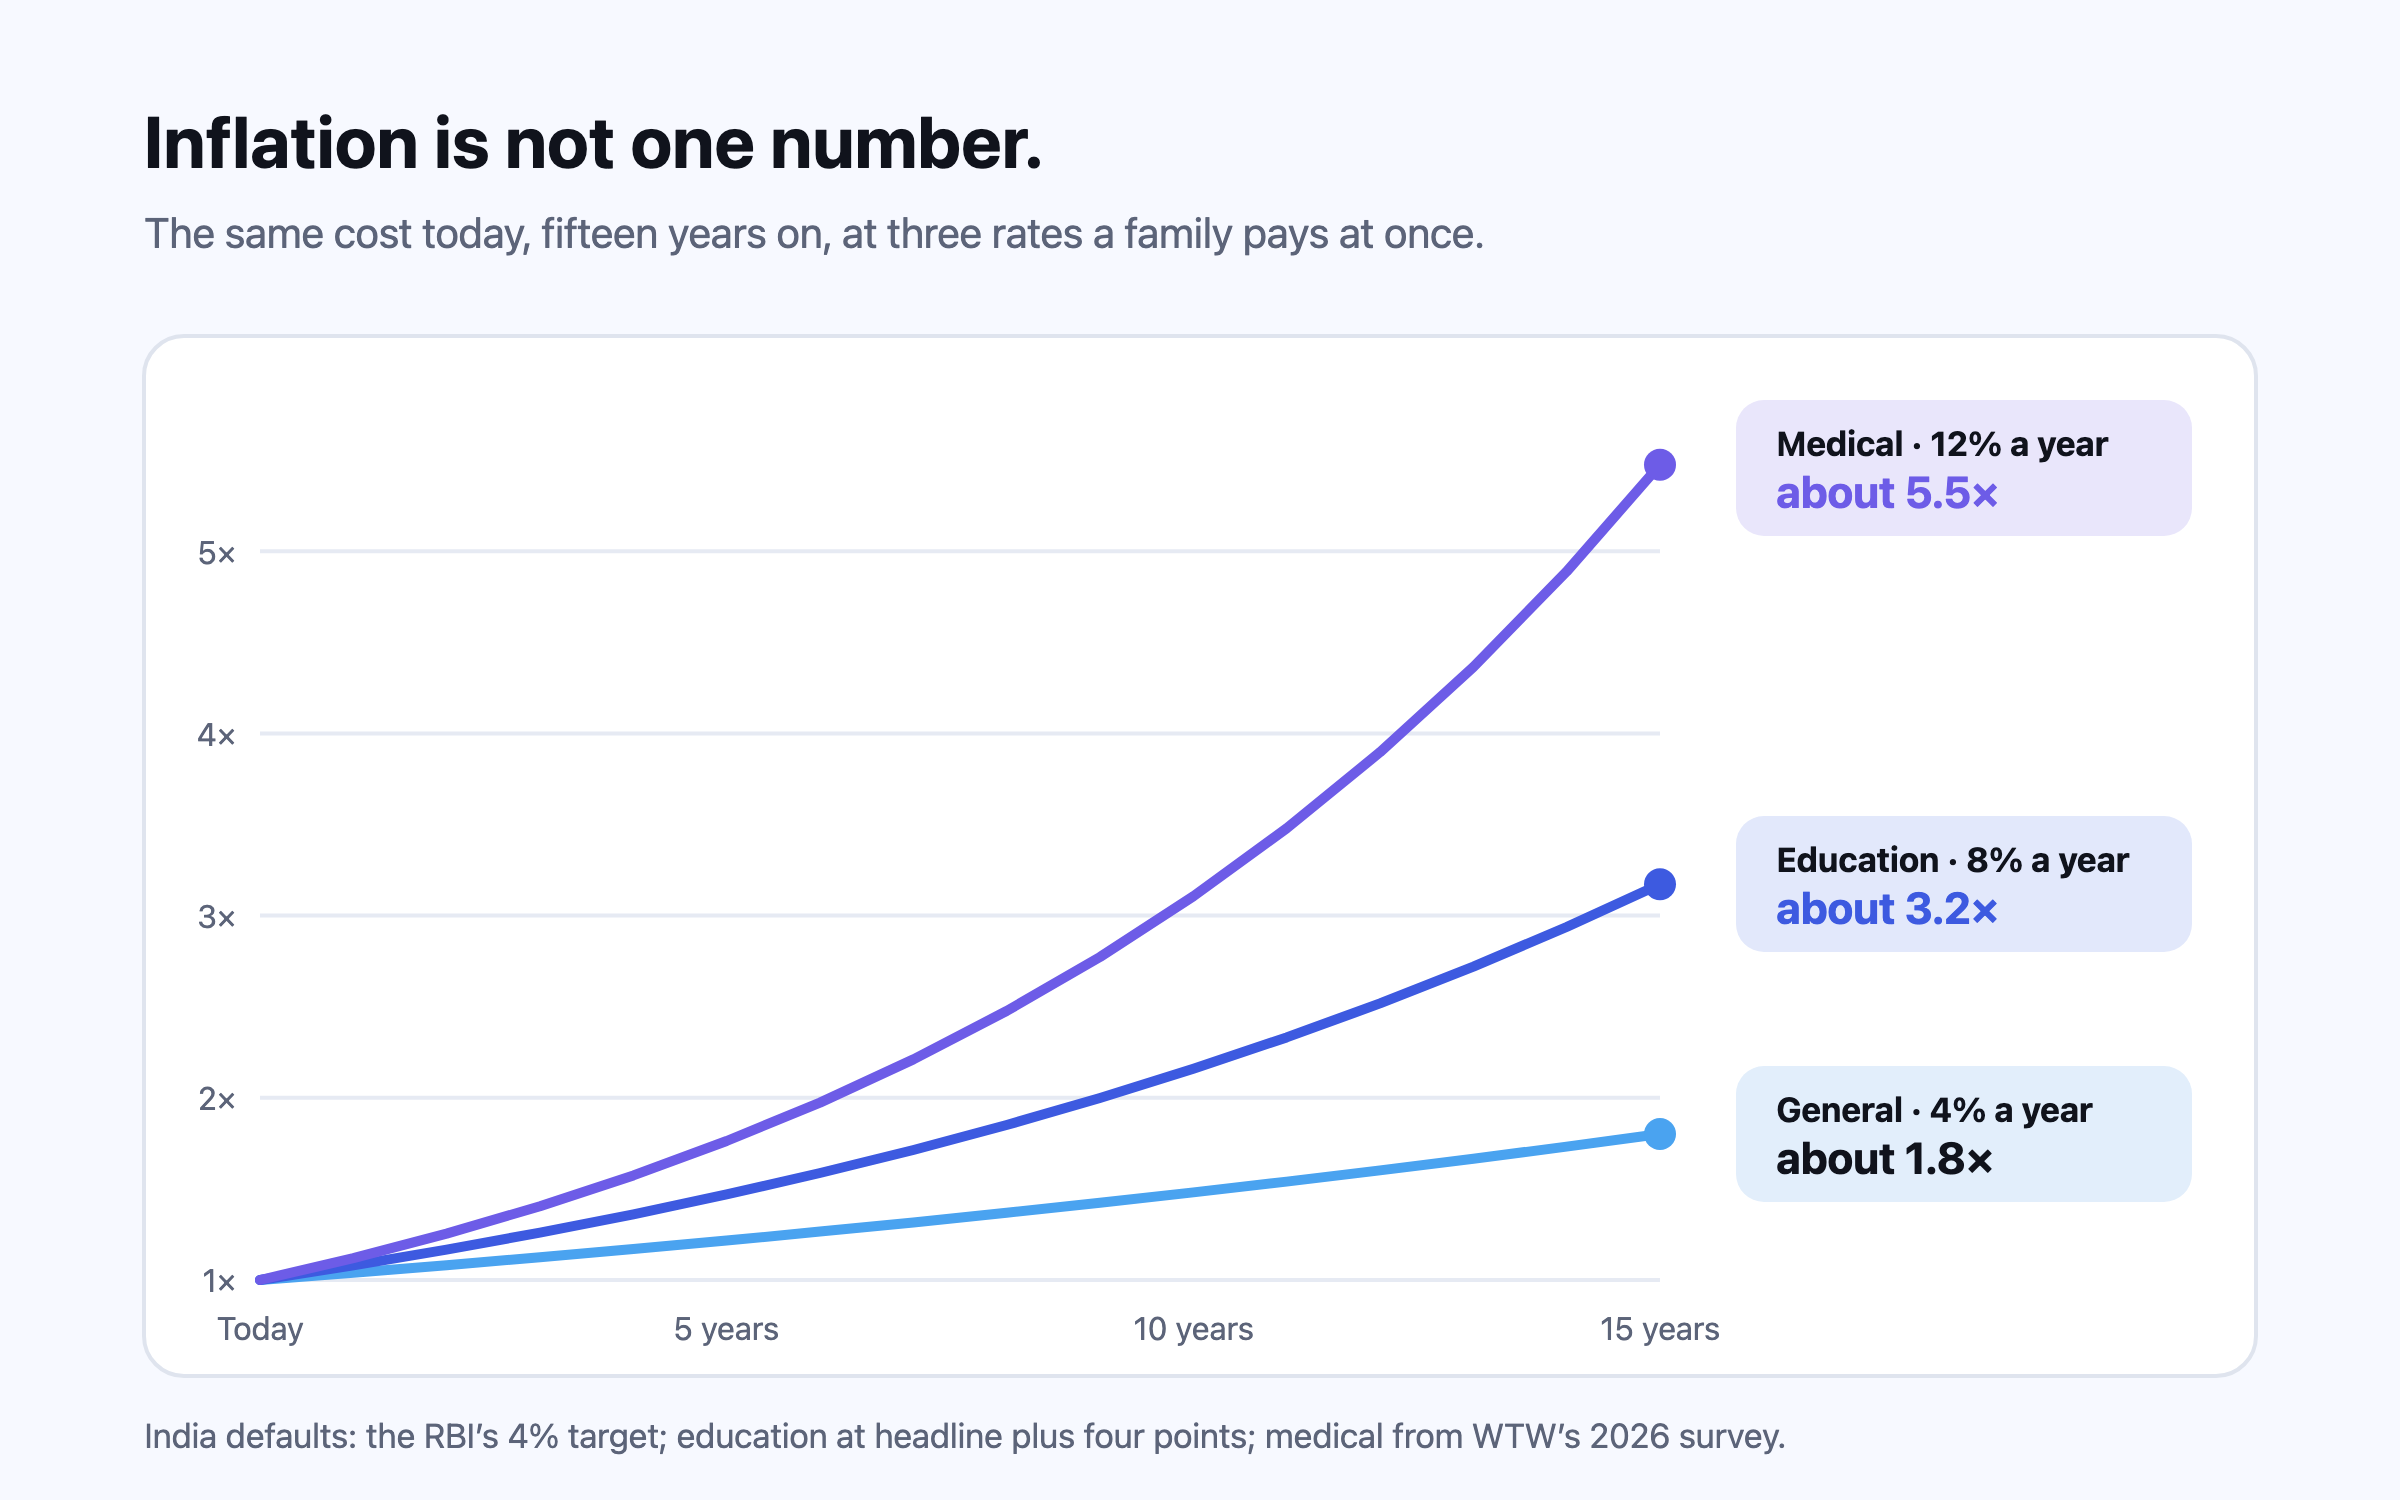
One inflation rate understates the cost that matters most to families: healthcare. In the defaults Nivritee projects with, general inflation runs 2.0–4.0% across fourteen markets, medical 2.7–16.9% and education 1.3–4.7% for school fees — measured over ten years, and below general inflation in six of the fourteen. University fees, measured separately, rose more slowly than general prices in eight. Over fifteen years, a cost rising at 12% grows to more than five times today’s figure; at 4%, to less than twice.
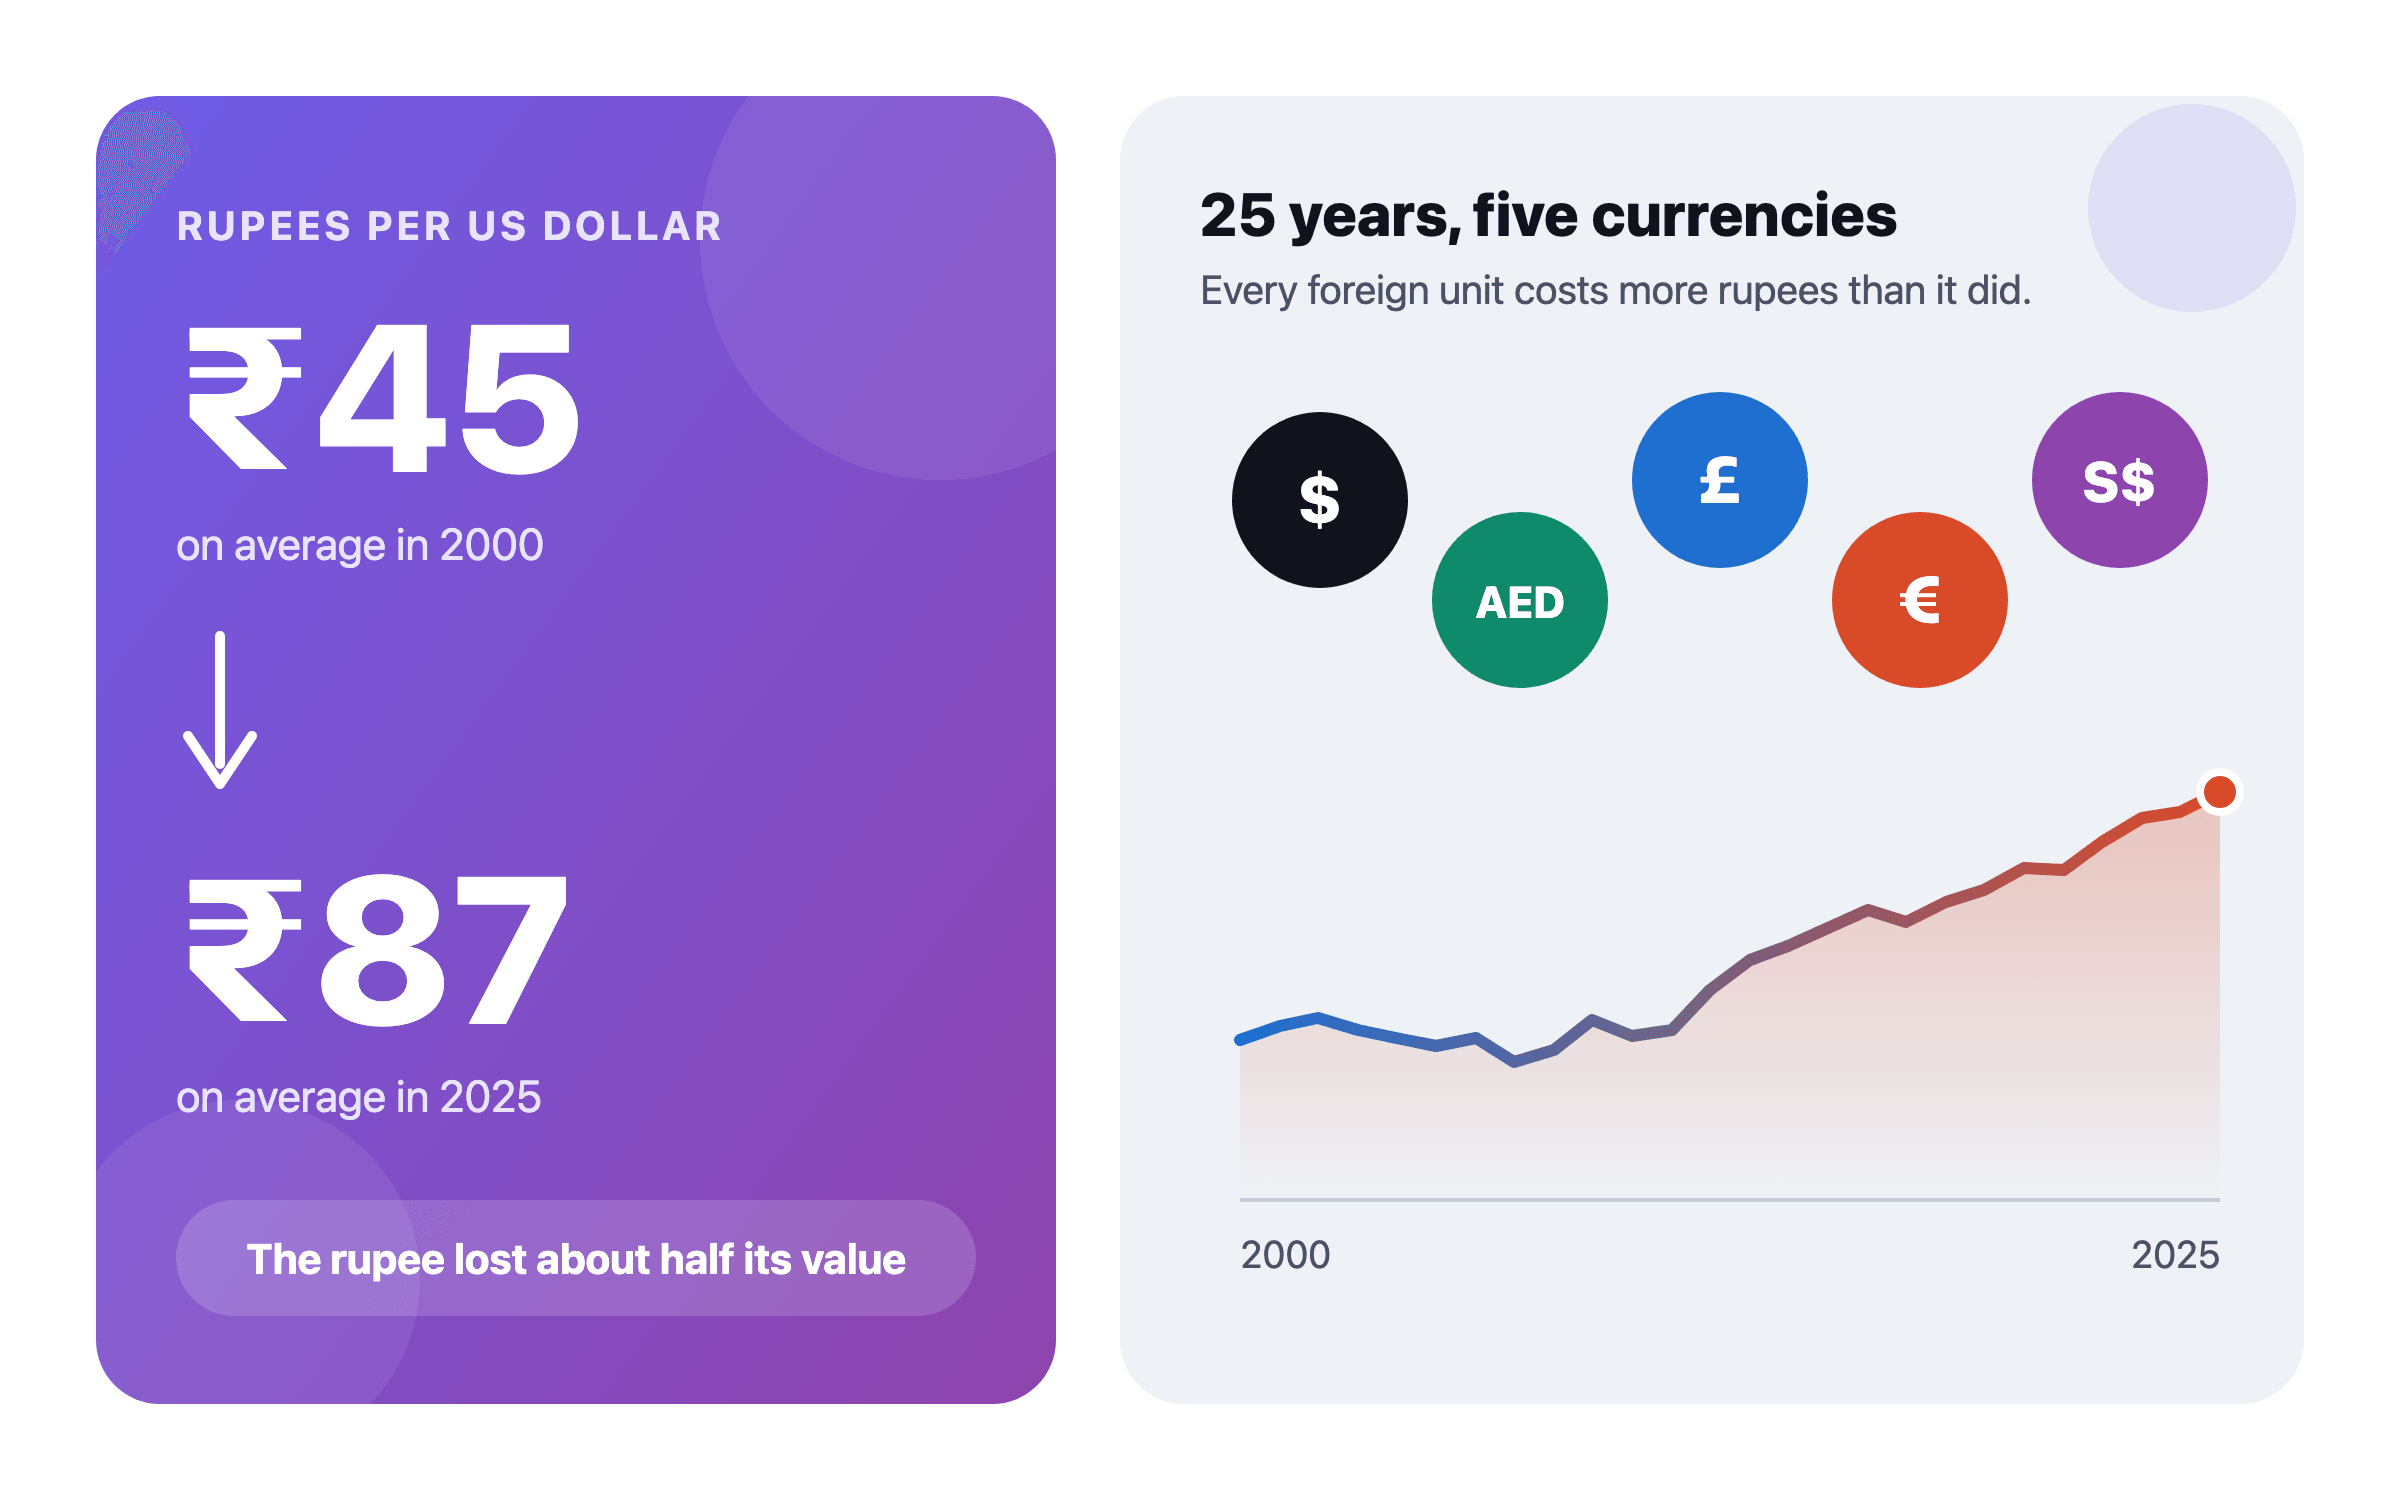
A dollar bought ₹45 on average in 2000 and ₹87 in 2025, a fall of about 2.7% a year, and the dirham moved exactly with it. The pound fell less and the euro and Singapore dollar more. Higher inflation in India explains the direction; for an NRI the lesson is to judge savings in the currency they will finally be spent in.
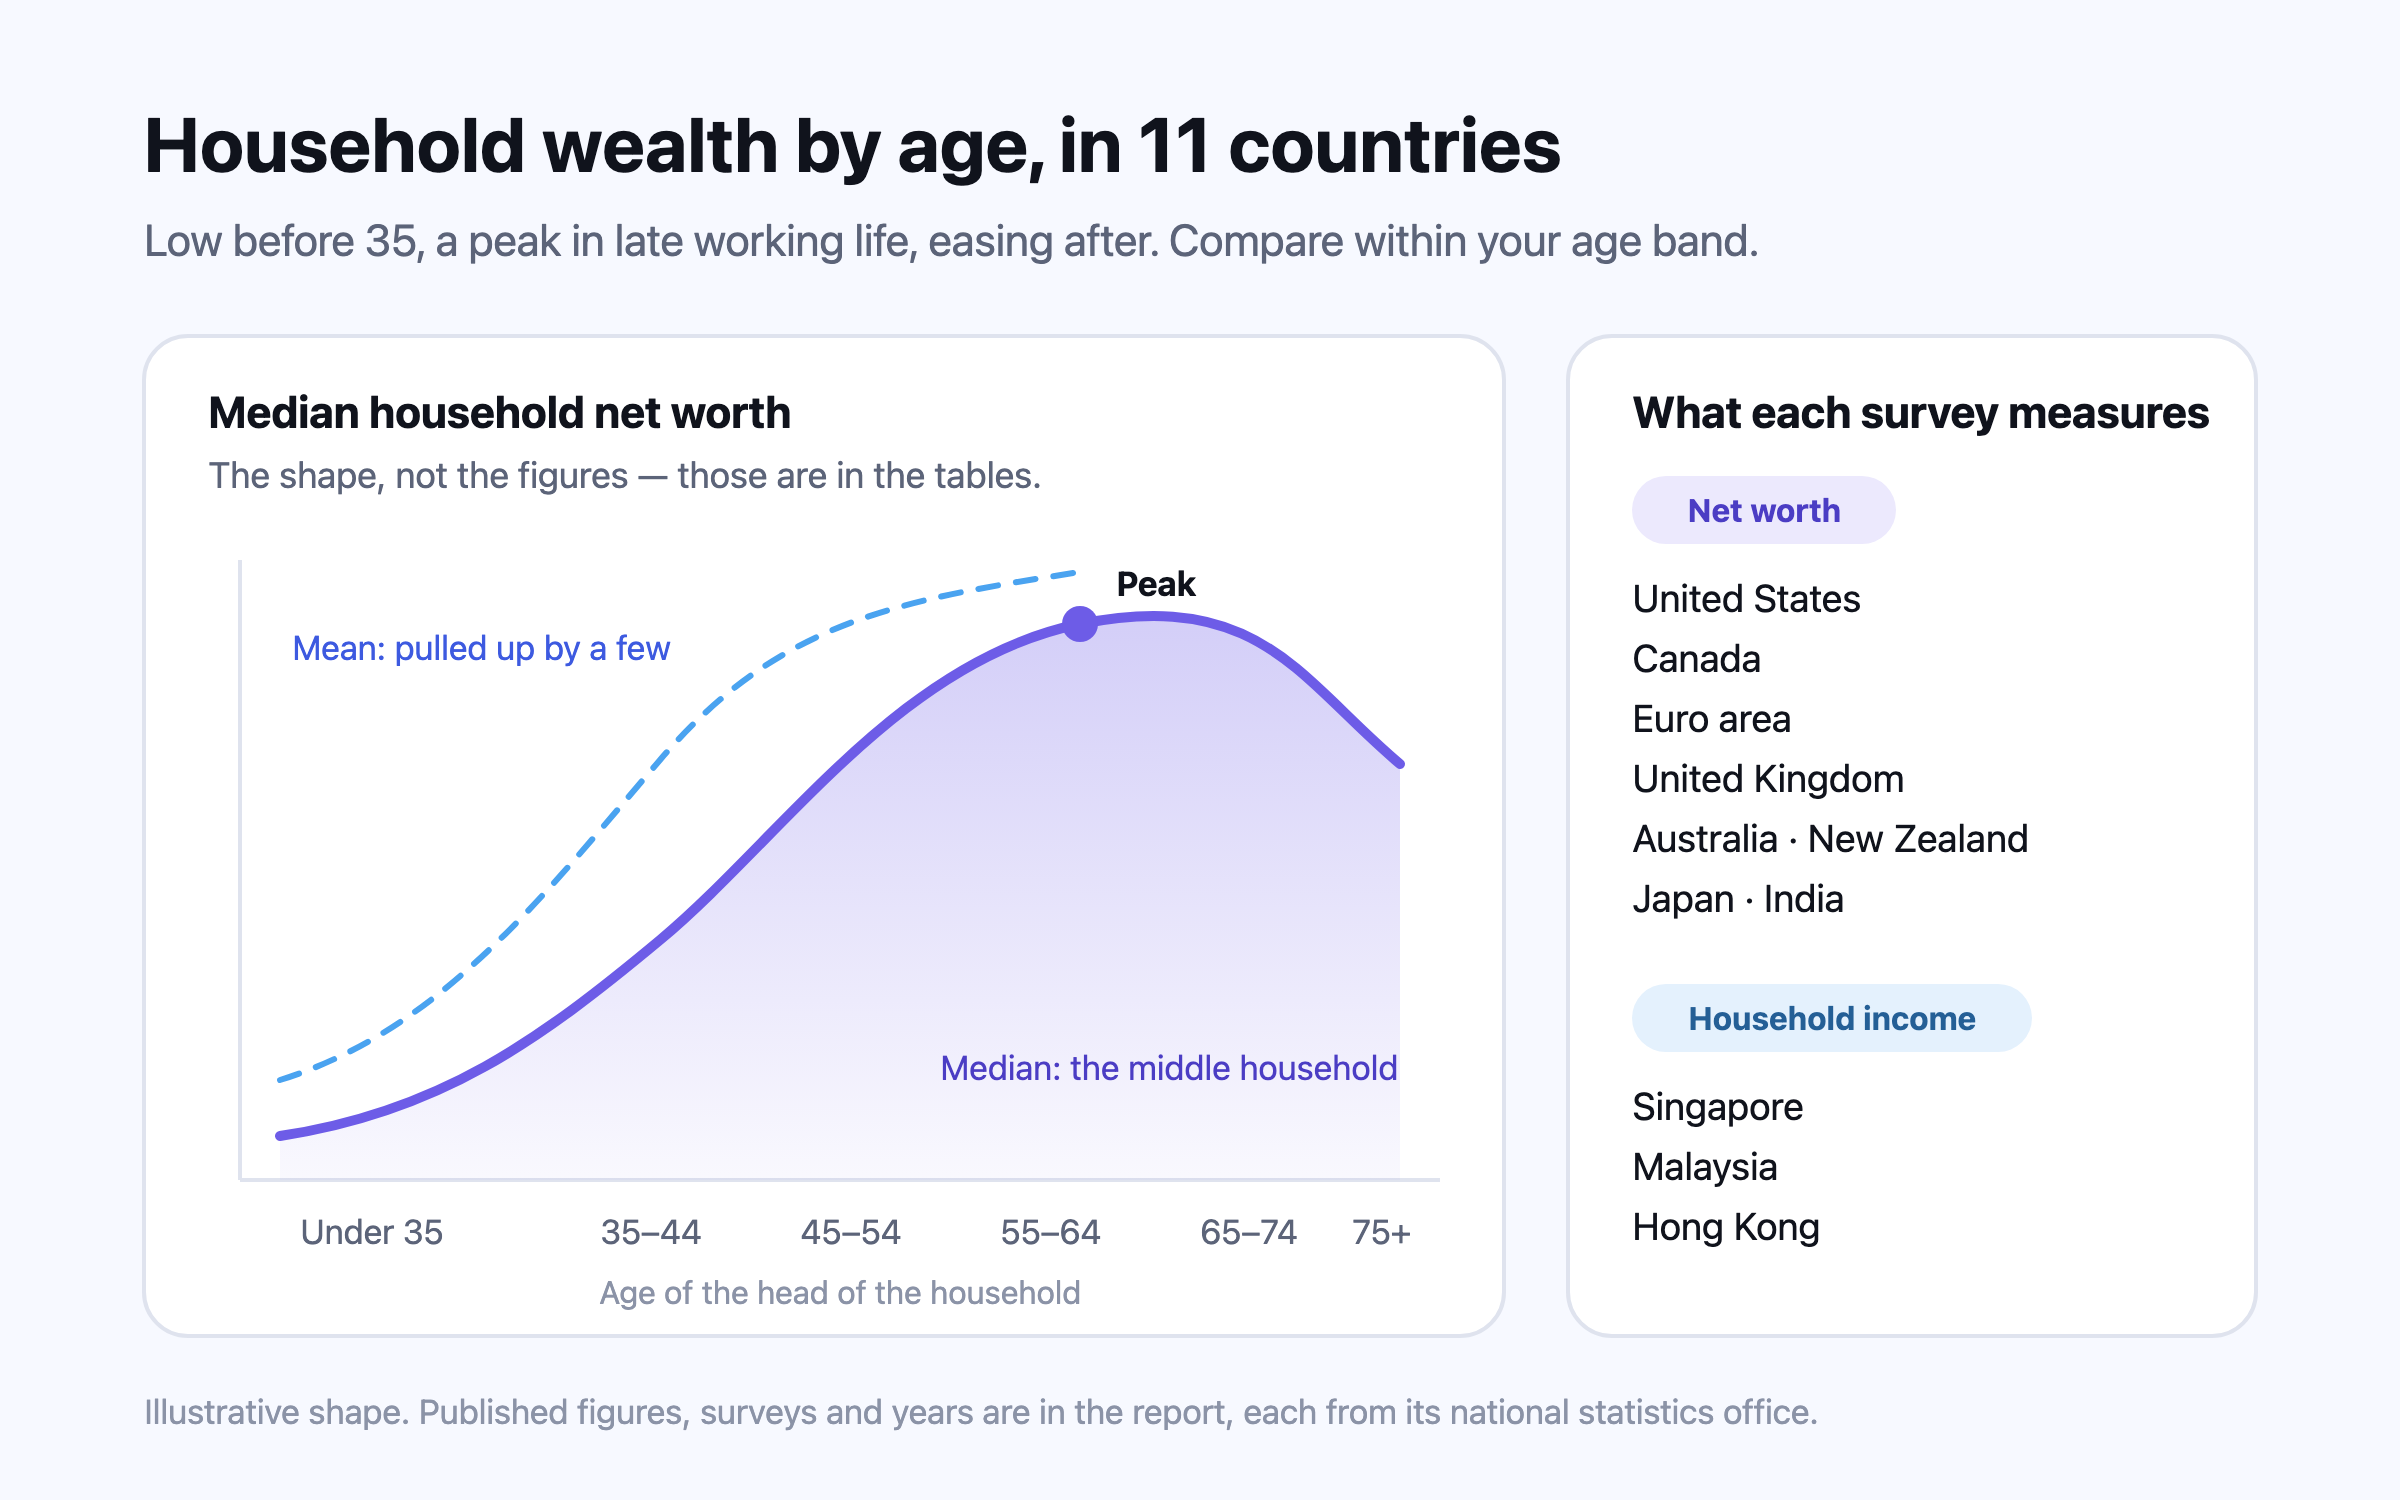
In every survey here, household wealth climbs steeply from the under-35s to a peak somewhere between 55 and 74, and the median sits far below the mean. Singapore, Malaysia, Hong Kong, Thailand and the Philippines publish household income rather than wealth, so for them the honest comparison is income; the UAE publishes neither, and is compared per adult against a UBS model.
This is general information, not financial, tax or legal advice for your circumstances. Rules and figures change; check the official source for your country, and consult a licensed professional before making financial decisions. Projections are estimates, not predictions.